


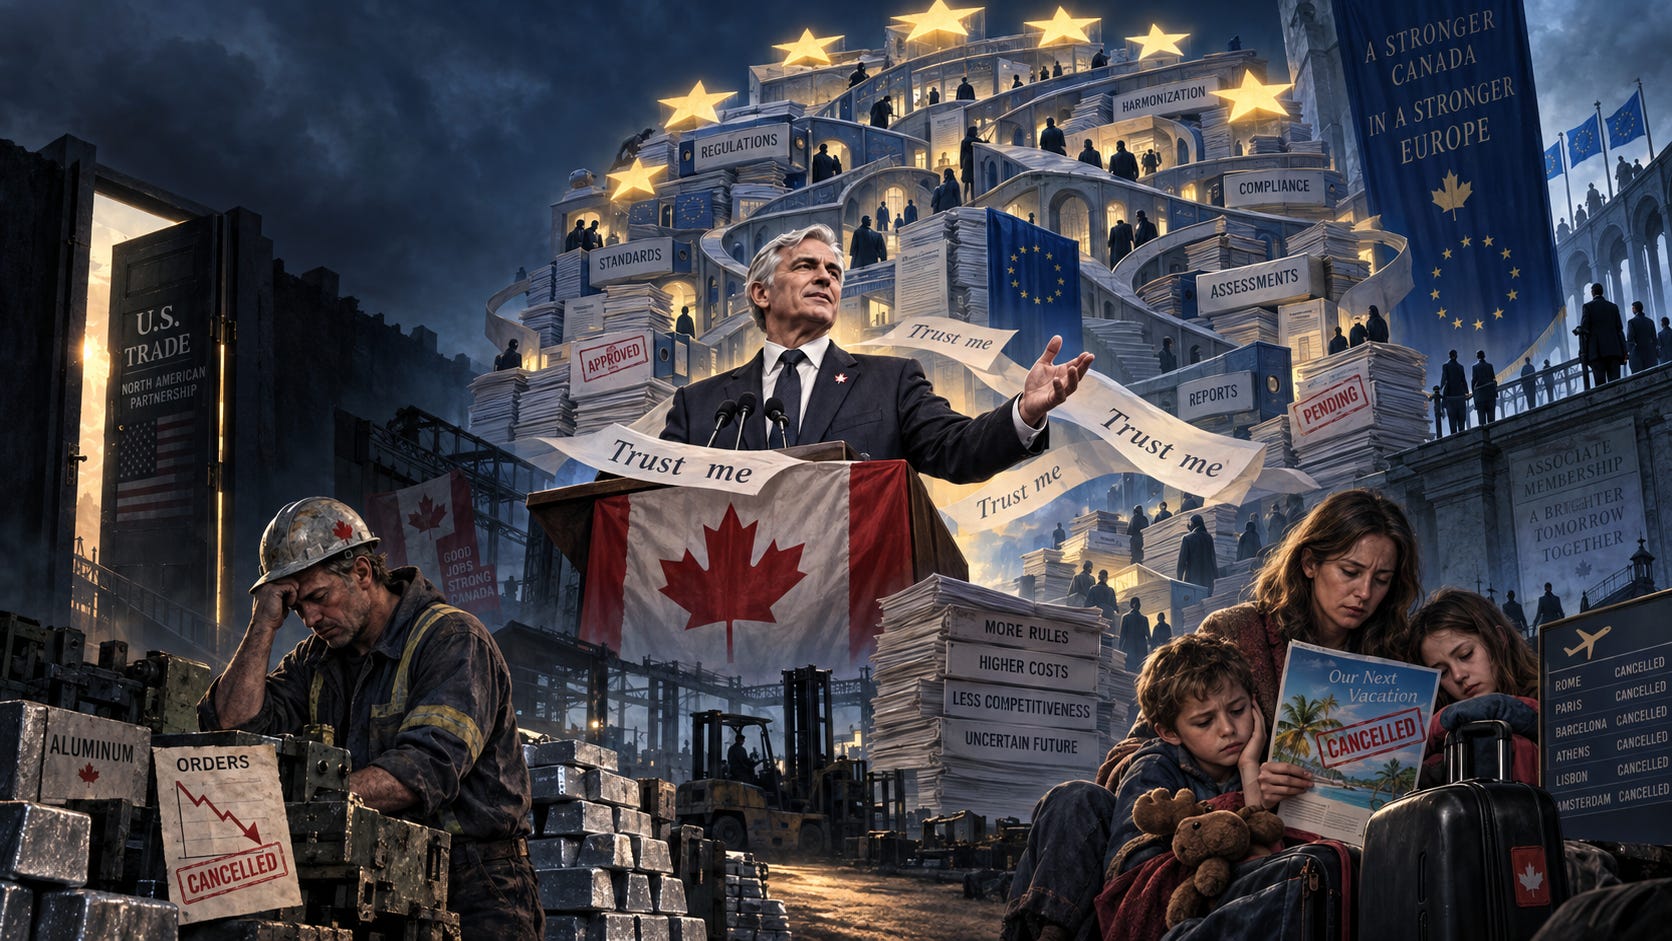
This is classic Carney: trust me. Trade talks with the United States break down, and Canadians are not shown the full negotiating record, the precise demands on either side, or a detailed accounting of what walking away will cost. Instead we get the emotional shorthand: Trump is unreasonable, Canada stood strong, trust me.
But “Canada strong” does not change my neighbour’s life.
He works in aluminum and tells me he has lost roughly 50% of his business because of the tariffs. That is not geopolitical theatre to him. It is whether the family vacation happens. Whether something gets fixed on the house. Whether money he expected to earn simply disappears.
Economics is not a chart. It is what people can and cannot do with their lives.
I understand that personally. When I lost my university professorship after the controversy surrounding my statement that I stood with Israel and my condemnation of Hamas, the consequences were concrete. I lost 1.8 million in future income.
There are things I expected to do that I cannot do now.
My retirement will be materially changed. I will eat, I will have a roof over my head, but job loss is granular, real; it is not some sterile number.
That is economics at ground level.
And now we get the European sequel: trust me.
Canada is suddenly supposed to become excited about EU “associate membership.” Except this is not a new free-trade agreement. We already have one. CETA has operated for years and already removed tariffs on almost all Canada-EU tariff lines. Canada already has research partnerships with Europe. Canadian universities already have European exchanges. Canadians already travel there. Governments have been pursuing European investment and trade diversification for decades.
Carney did not discover Europe.
What is supposedly new is a membership-style relationship whose exact meaning is still undefined. Carney has spoken of a “unique alliance,” and European officials themselves have acknowledged the vagueness surrounding the idea.
That should make Canadians obsessed with the fine print, because when most of the obvious upside already exists, the obligations become the issue.
What regulatory framework comes with deeper integration? What happens to Canadian energy, mining, aluminum, forestry, fertilizer and manufacturing? Europe already regulates market access aggressively, and Reuters has noted that deeper Canada-EU integration could require greater alignment with EU standards.
And then comes the fallback argument: “Ah, what harm could it do?”
Plenty.
That is an astonishingly weak standard for public policy. Europeans will negotiate for European interests. Canada should negotiate for Canadian interests. When the incremental upside is modest, the downside deserves more scrutiny, not less.
First: trust me, you don’t need the details.
Then: what harm could it do?
If that is how we make policy, we are in trouble.
The investment summit is the same problem in another costume.
The government announced “nearly $500 billion” of new investment and financing commitments. That is a spectacular headline. But it is not the same thing as half a trillion dollars of new foreign companies deciding to build factories, mines and productive capacity in Canada. The government’s own announcement bundles together different forms of financing and investment, while also unveiling a substantial new Productivity Mega Deduction for capital spending.
The deduction is a good idea.
But do we seriously think the underlying Canadian investment problem was that international investors had never heard of Canada? That a slick speech by a greasy political salesman will bring in billions?
Do we imagine that global pension funds, banks, private-equity firms and multinational corporations were sitting around saying, “Canada? Interesting. Why has nobody told us about this place?”
Of course not.
Investors come when the economics work.
They care about expected returns. Taxes. Permitting. Regulation. Infrastructure. Energy costs. Labour productivity. Political certainty. How many approvals they need. How long those approvals take. Whether a project can actually get built.
Canada’s federal general corporate tax rate remains 15%. Carney has introduced important investment deductions, and his government has said they will try to shorten federal project-review timelines and simplify some approval processes. Those are material steps and should be acknowledged. But they have not happened yet.
But that only reinforces the point.
That is the work that matters.
Fix the investment environment. Simplify approvals. Reduce duplication. Make major projects predictable. Improve productivity. Remove barriers. Make Canada a place where someone wants to risk $5 billion because the expected return is attractive and the project can actually be built.
That is harder than holding an investment summit.
It is also less glamorous. But our government seems more interested in spin and sexy branding that boosts Carney’s polling numbers, and less interested in the real heavy lifting that could lift Canada’s economy.
Statistics Canada says Canada attracted $96.8 billion in foreign direct investment in 2025, the strongest annual inflow since 2007. But $43.6 billion of that was mergers and acquisitions. Buying an existing Canadian company is economically different from building a new factory, mine or production line.
Again, the real story is underneath the headline.
And this is where I think the Carney problem becomes much larger than one summit or one European initiative. There is a growing disconnect between what increases political popularity and what materially improves Canada.
Flying to Europe produces photographs. Speaking to the European Parliament produces applause. Announcing $500 billion produces headlines. Standing up to Trump produces patriotic emotion. Investment summits produce impressive rooms full of impressive people.
The heavy lifting of governance is different.
It means cutting years of regulatory delay, making projects economically viable, and confronting hard tax and spending choices. Above all, it means challenging the statist interests that helped bring Carney to power.
Canada’s protected, sclerotic economy has a political constituency: bureaucracies and entrenched interests that benefit from the status quo and form part of the Liberal base. Reform risks alienating them.
Staging another PR carnival—with prosperity forever just around the corner—keeps them comfortable, gives credulous voters something to applaud, and supplies friendly media with another headline.
The political cost is small. The real bill goes to people like my neighbour, and the single mother who cannot afford decent meat for her children.
It means improving productivity. It means creating an environment in which investment comes because investors genuinely want to invest, not because the prime minister has become Canada’s travelling salesman.
And when political incentives repeatedly reward the first category more than the second, politicians have an obvious temptation to choose the branding.
That is the irony of the Carney brand. He is marketed as the supreme technocrat, the economist, the numbers guy, the sober adult who rises above political theatre.
Yet so much of the political product is theatre.
Stand up to Trump.
Wrap yourself in the flag.
Embrace sophisticated Europe.
Announce enormous investment numbers.
Trust me.
There is a whiff of Euro snobbery in the whole exercise, mixed with anti-Americanism. But real economics is happening far below all of that.
Somebody loses an aluminum order.
Somebody loses overtime.
Somebody’s business falls 50%.
Somebody cancels the family vacation.
Somebody postpones a renovation.
Somebody loses a job and discovers that plans made when income seemed secure are no longer possible.
That is economics.
So spare me “trust me.”
And spare me “what harm could it do?”
Tell us exactly what Canada gets from European associate membership that we do not already possess. Tell us what obligations come with it. Tell us what regulatory alignment might mean for Canadian industry. When you announce hundreds of billions of dollars in investment, tell us how much represents genuinely new productive capacity and how much consists of financing, buying our bonds, acquisitions and commitments that would have happened anyway.
And then do the hard work.
Because a government should be judged less by the size of its announcements than by whether ordinary Canadians can actually do more with their lives.
This essay was dictated into AI. The image was created with AI. I used AI for formatting and grammar screening. All of the ideas, arguments, flow, metaphors and conclusions came directly from my words.
Prime Minister Carpetbagger is selling us down the river again. I am sure the Eurocrats are cooking up a windfall tax scheme to be applied against Alberta oil revenues to fund whatever the green grift dejour might be. Why can’t we have someone negotiate arrangements on Canada’s behalf that facilitates our nation’s entrepreneurs to sell more things to more people in more places? Instead we have leaders who seem intent on putting us in entangling alliances under the banner of feel-good slogans.